By Roberto Gomes | Updated October 2026. This guide compares published 2026 rate studies from NerdWallet and ValuePenguin with official information from the Florida Department of Highway Safety and Motor Vehicles (FLHSMV), the Florida Office of Insurance Regulation (OIR), the Florida Statutes, the Miami-Dade Sheriff’s Office and the National Insurance Crime Bureau. Prime Capital Report does not sell insurance and is not a licensed agent. Every price below is an average or median from the source named next to it, so your own quote will be different.
The best car insurance in Miami is the policy that protects you properly at a price you can sustain, from a company that pays claims fairly. In 2026, GEICO is the cheapest large insurer for a typical Miami driver in both studies we reviewed, with State Farm, Travelers and UAIC next in line depending on your record and credit. Miami is one of the most expensive places in the country to insure a car. Florida’s no-fault system, a high share of uninsured drivers, dense traffic and storm flooding all push prices up. The good news is that Florida rates are now falling: the state’s five largest auto insurers are indicating an average 8% cut for 2026, according to OIR. That makes this a good year to re-shop.
Key takeaways
- Miami costs far more than average: NerdWallet’s October 2026 median for full coverage is $4,452 a year in Miami, compared with $3,295 for Florida and $2,361 nationally.
- Lowest prices in the studies: GEICO had the lowest median in NerdWallet’s Miami data ($2,267 a year) and the lowest average in ValuePenguin’s ($185 a month).
- Best overall: ValuePenguin names State Farm the best car insurance in Miami for its mix of price, J.D. Power satisfaction and low complaint levels.
- Legal minimum: $10,000 of personal injury protection (PIP) and $10,000 of property damage liability (PDL), according to FLHSMV. Bodily injury liability isn’t required for most drivers.
- Rates are dropping: OIR says Florida’s top five auto insurance groups are indicating an average −8% rate change for 2026.
- Uninsured drivers are common: an estimated 20.6% of Florida drivers were uninsured in 2023, according to the Insurance Research Council.
How much does car insurance cost in Miami?
Each study uses a different sample driver, car and coverage level, so their averages don’t match. That’s why we show them side by side instead of blending them. The pattern is clear in both: Miami is well above the Florida average, and Florida is well above the national average.
| Measure | Miami | Florida | United States | Source |
|---|---|---|---|---|
| Full coverage, median per year | $4,452 | $3,295 | $2,361 | NerdWallet, Oct 2026 |
| Full coverage, average per month | $349 | $272 | n/a | ValuePenguin Miami, Sep 25, 2026 |
| Minimum coverage, average per month | $140 | $102* | n/a | ValuePenguin Miami / Florida |
Sources: NerdWallet, Cheap Car Insurance in Miami for October 2026 (updated Oct. 2, 2026). NerdWallet, Average Car Insurance Cost in 2026. ValuePenguin, Best Cheap Car Insurance in Miami (updated Sep. 25, 2026). *Florida minimum-coverage average from ValuePenguin’s Florida study (updated Oct. 13, 2026), which uses a 2018 Honda Civic.
In NerdWallet’s data, the typical Miami driver pays about 35% more than the typical Florida driver ($4,452 vs. $3,295) and nearly 90% more than the national median. ValuePenguin says Florida car insurance overall is about 55% more expensive than the national average. In its statewide city table, Miami averages $401 a month for full coverage, compared with $371 in Fort Lauderdale, $314 in Orlando and $300 in Jacksonville. Neighboring Hialeah ($428) and North Miami ($431) cost even more.
Best car insurance companies in Miami

NerdWallet: cheapest companies for a 35-year-old good driver
NerdWallet analyzed rates for male and female drivers in every Miami ZIP code using a 2023 Toyota Camry LE. Full coverage included 100/300/50 liability, 100/300 uninsured motorist coverage, Florida’s required PIP and $1,000 deductibles. The table shows median annual rates for a 35-year-old with good credit and a clean record.
| Company | Full coverage (median per year) | Per month (est.) |
|---|---|---|
| GEICO | $2,267 | $189 |
| UAIC | $3,317 | $276 |
| Travelers | $4,414 | $368 |
| Mercury | $4,472 | $373 |
| Allstate | $7,224 | $602 |
| Direct Auto | $9,243 | $770 |
| Miami median | $4,452 | $371 |
Source: NerdWallet (updated Oct. 2, 2026; Quadrant Information Services data). Monthly figures are our estimate (annual ÷ 12). UAIC is United Automobile Insurance Company. NerdWallet excluded Liberty Mutual because its rates weren’t available.
ValuePenguin: Miami results
ValuePenguin’s Miami page is built on 41,328 quotes from seven companies across 56 Miami ZIP codes. Its sample driver is a 30-year-old man with good credit and a 2015 Honda Civic EX, with 50/100/25 liability, $10,000 of PIP, matching uninsured motorist limits and $500 deductibles. GEICO is cheapest at $185 a month for full coverage, roughly half the Miami average, and $48 a month for minimum coverage.
| Company | Full coverage (avg. per month) | Minimum liability (avg. per month) |
|---|---|---|
| GEICO | $185 | $48 |
| State Farm | $236 | $96 |
| Travelers | $251 | $90 |
| UAIC | $312 | $169 |
| Progressive | $395 | $170 |
| Allstate | $521 | $215 |
| Farmers | $543 | $191 |
| Miami average | $349 | $140 |
Source: ValuePenguin, Miami (updated Sep. 25, 2026).
Both studies agree on GEICO at the top for clean-record drivers, which is unusual. ValuePenguin’s statewide study agrees too: GEICO is cheapest in Miami at $224 a month with a 2018 Civic. Where they differ is the runner-up, because NerdWallet’s Miami table doesn’t include State Farm. The practical lesson: get quotes from GEICO and State Farm, plus Travelers or UAIC, and add Mercury if you have a young driver or a ticket.
Customer service and financial strength
ValuePenguin calls State Farm the best car insurance in Miami because of its high J.D. Power customer satisfaction score and because it gets significantly fewer complaints than average for its size, according to NAIC data. It describes GEICO’s service reputation as “middle of the road.” It also warns that State Farm is a poor choice if you have a DUI or poor credit. Here are the Florida scores it reports.
| Company | J.D. Power 2025 customer satisfaction score | AM Best financial strength |
|---|---|---|
| State Farm | 650 | A++ |
| GEICO | 645 | A++ |
| Allstate | 635 | A+ |
| Progressive | 621 | A+ |
| Travelers | 613 | A++ |
Source: ValuePenguin, Florida (updated Oct. 13, 2026), citing the J.D. Power 2025 U.S. Auto Insurance Study and AM Best. You can check any insurer’s complaint record with the NAIC Consumer Insurance Search.
Best car insurance in Miami by driver profile
Young drivers
Miami is brutal for young drivers. NerdWallet’s citywide median for a 20-year-old is $9,779 a year, more than double the 35-year-old median. UAIC was cheapest at that age ($5,173), followed by GEICO ($5,588) and Mercury ($7,561). For 18-year-olds, ValuePenguin found GEICO far ahead: $112 a month for liability only and $501 for full coverage, against city averages of $371 and $1,052. ValuePenguin suggests good-GPA and safety-course discounts for teens.
Drivers with a speeding ticket
In NerdWallet’s data, GEICO’s median after one speeding ticket ($2,267) was the same as its clean-record median. ValuePenguin found State Farm cheapest after a ticket at $256 a month, about 38% below the $416 city average, with Travelers at $309.
Drivers with an accident
GEICO is cheapest after an at-fault accident in both studies: $3,249 a year in NerdWallet’s data (then UAIC at $4,275) and $259 a month in ValuePenguin’s (then State Farm at $278), about half the $507 city average. ValuePenguin notes your rate usually won’t rise until renewal, so shop when your policy is about to expire.
Drivers with a DUI
NerdWallet found GEICO cheapest after a DUI at $4,094 a year, followed by UAIC ($5,735). ValuePenguin ranks Travelers first at $398 a month, with GEICO close at $409, against a $557 city average. ValuePenguin says a DUI raises Miami rates by $208 a month on average.
Drivers with poor credit
Florida insurers use credit-based insurance scores, NerdWallet notes. UAIC is cheapest for poor credit in both studies: $3,317 a year in NerdWallet’s data (the same as its good-credit median) and $312 a month in ValuePenguin’s. GEICO follows ($4,313 a year; $351 a month). State Farm jumps to $1,387 a month for poor credit in ValuePenguin’s data.
Mature drivers
NerdWallet’s Miami median drops to $3,305 a year at age 60. GEICO ($2,054), UAIC ($2,873) and Mercury ($2,951) had the lowest 60-year-old medians.
Car insurance costs by Miami ZIP code
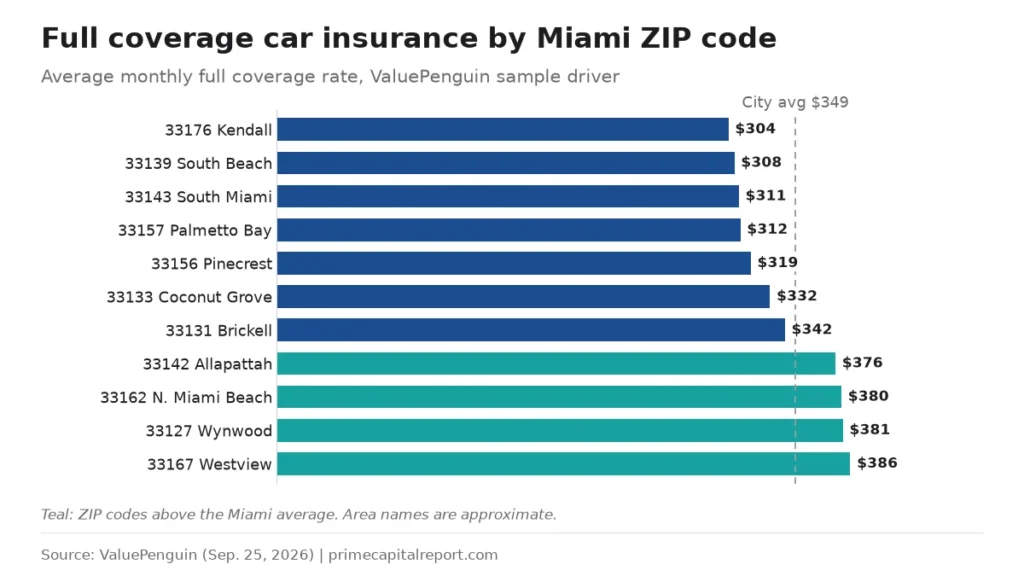
Insurers price by ZIP code because theft, vandalism and traffic differ across the city. ValuePenguin found Kendall the cheapest Miami neighborhood and Westview the most expensive, with an $82-a-month gap between them. Here is a selection from its ZIP table.
| ZIP code | Area | Full coverage (avg. per month) | vs. city average |
|---|---|---|---|
| 33176 | Kendall | $304 | −12% |
| 33139 | Miami Beach (South Beach) | $308 | −11% |
| 33143 | South Miami | $311 | −10% |
| 33157 | Palmetto Bay / Cutler Bay area | $312 | −10% |
| 33156 | Pinecrest | $319 | −8% |
| 33133 | Coconut Grove | $332 | −4% |
| 33131 | Brickell | $342 | −1% |
| 33142 | Allapattah area | $376 | +9% |
| 33162 | North Miami Beach | $380 | +10% |
| 33127 | Wynwood area | $381 | +10% |
| 33167 | Westview | $386 | +12% |
Source: ValuePenguin, Miami (updated Sep. 25, 2026; 2015 Honda Civic sample driver). Area names are approximate. Use these figures to compare parts of the city with each other, not as a price quote.
NerdWallet’s data for Miami’s most populated ZIP codes shows the same pattern at a higher price level. Its full coverage medians run from $3,811 a year in 33157 to $4,665 in 33125, with 33161 close behind at $4,663.
Why car insurance is more expensive in Miami
Traffic and crashes
Miami-Dade is Florida’s crash capital. FLHSMV’s 2024 Traffic Crash Facts report shows 60,000 crashes, 272 deaths and 29,359 injuries in Miami-Dade County in 2024. That’s about 16% of Florida’s 381,423 crashes. The trend is improving: crashes fell 6.26% and deaths fell 16.31% from 2023. Injury claims are expensive, and in a no-fault state your own PIP pays first.
Vehicle theft
Florida had 27,142 vehicle thefts in 2025, the fourth-most of any state, according to NICB. But it also posted one of the biggest drops in the country, down 29% from 2024. Locally, the Miami-Dade Sheriff’s Office reports 2,699 motor vehicle thefts in 2025 in the areas it patrols (unincorporated Miami-Dade and contract cities), down from 3,485 in 2024. That’s a 22.6% decline.
Storms and flooding
ValuePenguin points to severe weather, including flooding from storm surge and fallen branches, as a reason Florida rates are high. Hurricanes produce auto claims even far from the eye. When Hurricane Isaias struck the Panhandle in October 2026, insurers reported 4,136 private passenger auto claims statewide in OIR’s catastrophe data as of Oct. 15, 2026. Only comprehensive coverage pays for flood or storm damage to your own car.
Uninsured drivers
The Insurance Research Council estimates that 20.6% of Florida drivers were uninsured in 2023, the seventh-highest rate in the country and well above the national 15.4%, according to the Insurance Information Institute. Triple-I notes that Florida’s compulsory law covers PIP and property damage but not bodily injury liability. That makes uninsured motorist coverage especially important in Miami.
Florida car insurance requirements
FLHSMV says every vehicle with a current Florida registration must carry at least:
- Personal injury protection (PIP): $10,000. PIP covers 80% of necessary and reasonable medical expenses up to $10,000 from a covered injury, no matter who caused the crash.
- Property damage liability (PDL): $10,000, which pays for damage you cause to other people’s property.
ValuePenguin adds that PIP also covers 60% of lost income, within the same $10,000 limit. Bodily injury liability isn’t part of the basic requirement, but FLHSMV notes it can be required to reinstate your license after certain crashes or violations (through an SR-22 filing). If you cause a serious crash without it, you can be sued personally. Most drivers with assets should carry at least 100/300 bodily injury liability plus uninsured motorist coverage, and more than $10,000 of property damage. A $10,000 limit won’t replace most new cars, as ValuePenguin notes.
You must keep PIP and PDL in force for the whole registration period. FLHSMV says a lapse can lead to suspension of your license and plate for up to three years and a reinstatement fee of up to $500, with no hardship license for insurance suspensions. If you plan to cancel your insurance, FLHSMV advises turning in your plate first to avoid suspension and reinstatement fees. If no private company will insure you, ValuePenguin points to the Florida Automobile Joint Underwriting Association (FAJUA), a state-run option.
No-fault and the 51% fault rule
Florida is a no-fault state for injuries: your own PIP pays your first medical costs regardless of who caused the crash. For lawsuits, Florida now uses modified comparative negligence. Under Section 768.81 of the Florida Statutes, a person found more than 50% at fault for their own harm can’t recover damages (with an exception for medical negligence cases).
Are Miami car insurance rates going down in 2026?
Yes, for most drivers. OIR says Florida’s top five auto insurance groups (Progressive, GEICO’s parent Berkshire Hathaway, State Farm, Allstate and USAA), which write 78% of the market, are indicating an average −8% rate change for 2026, with one group at −16.5%. They requested a total −7.4% for 2025. ValuePenguin’s Florida filing data, current as of Oct. 6, 2026, shows State Farm down 10.2%, Auto-Owners 8.6%, USAA 7.0%, Allstate 5.3% and GEICO 4.2% for 2026. American Family had the biggest increase (+3.6%). If your renewal didn’t go down, that’s a strong signal to shop.
Car insurance discounts in Florida
- Low mileage: NerdWallet suggests mentioning it if you work from home.
- Bundling and multi-car: combining auto with home, condo or renters insurance, or insuring several cars.
- Student and good-GPA discounts: common for teen drivers, according to ValuePenguin and NerdWallet.
- Safety courses: ValuePenguin notes many companies discount teens who complete one.
- Paperless, online and automatic payments: ValuePenguin says you can save by getting a quote online, quoting before your policy expires or signing up for automatic payments with some insurers.
- Life changes: NerdWallet says many companies offer lower rates for married couples or domestic partners.
How to save on car insurance in Miami
- Compare at least three quotes with identical coverage. Match PIP, liability, uninsured motorist limits and deductibles. Our guide on how to compare car insurance quotes walks through it.
- Start with GEICO and State Farm. Then add Travelers, UAIC or Mercury depending on your record and credit.
- Re-shop at renewal in 2026. With most large insurers filing cuts, your current company may not pass the full decrease to you.
- Don’t skimp on uninsured motorist coverage. One in five Florida drivers may be uninsured.
- Raise deductibles instead of dropping comprehensive. Flood and theft risks make comprehensive valuable in Miami.
- Revisit quotes three to five years after a violation. NerdWallet notes tickets and accidents may drop off your record by then.
- Never let coverage lapse. A lapse risks suspension and up to $500 in reinstatement fees.
Comparing cities? See our guides to the best car insurance in Chicago, the best car insurance in Louisiana and the cheapest car insurance in Texas.
Our methodology
Prime Capital Report doesn’t collect insurance quotes. We compared current, dated rate studies and used official sources for laws and statistics. We don’t mix sources inside one ranking, because each study uses a different driver profile.
- NerdWallet Miami (updated Oct. 2, 2026): median Quadrant Information Services rates for all Miami ZIP codes, 2023 Toyota Camry LE, 35-year-old base driver.
- ValuePenguin Miami (updated Sep. 25, 2026): 41,328 quotes, seven companies, 56 Miami ZIP codes, 30-year-old man with a 2015 Honda Civic EX.
- ValuePenguin Florida (updated Oct. 13, 2026): 442,470 quotes, 1,031 ZIP codes, 2018 Honda Civic EX. Rate-filing data is as of Oct. 6, 2026.
- Official and industry data: FLHSMV insurance requirements and 2024 Traffic Crash Facts, Florida OIR (March 5, 2026 release and Hurricane Isaias claims data as of Oct. 15, 2026), Florida Statutes §768.81, Miami-Dade Sheriff’s Office 2025 Annual Report, NICB (March 18, 2026) and the Insurance Research Council via Triple-I (2023 data).
Monthly figures marked “est.” are annual figures divided by 12. We’ll update this page when the sources publish new data.
Frequently asked questions
What is the best car insurance company in Miami?
For price, GEICO: it had the lowest median full coverage rate in NerdWallet’s October 2026 Miami data ($2,267 a year) and the lowest average in ValuePenguin’s ($185 a month). For overall value and service, ValuePenguin names State Farm the best in Miami, though it’s expensive after a DUI or with poor credit.
How much is car insurance in Miami per month?
NerdWallet’s October 2026 median for full coverage in Miami is $4,452 a year, or about $371 a month. ValuePenguin’s Miami average is $349 a month for full coverage and $140 for minimum coverage.
Why is car insurance so expensive in Miami?
Heavy traffic, a high share of uninsured drivers and storm risk. Miami-Dade had 60,000 crashes and 272 traffic deaths in 2024, according to FLHSMV, and an estimated 20.6% of Florida drivers were uninsured in 2023.
What is the minimum car insurance required in Miami?
Miami follows Florida law: $10,000 of personal injury protection (PIP) and $10,000 of property damage liability (PDL), according to FLHSMV. Bodily injury liability isn’t part of the basic requirement, but it’s strongly recommended.
Is Florida a no-fault state?
Yes. Your own PIP pays 80% of your medical costs up to $10,000 regardless of who caused the crash. For lawsuits, Florida Statutes §768.81 bars recovery if you’re more than 50% at fault for your own harm.
Which Miami ZIP codes have the cheapest car insurance?
In ValuePenguin’s data, 33176 (Kendall) was cheapest at $304 a month for full coverage, followed by 33139 (Miami Beach) at $308 and 33143 (South Miami) at $311. Westview (33167) was the most expensive at $386.
Are Florida car insurance rates going down?
Yes, on average. The Florida Office of Insurance Regulation says the state’s top five auto insurance groups, with 78% of the market, are indicating an average −8% rate change for 2026, after −7.4% requested for 2025.
Sources
- NerdWallet, “Cheap Car Insurance in Miami for October 2026,” updated Oct. 2, 2026: https://www.nerdwallet.com/insurance/auto/cheap-car-insurance-miami-fl
- NerdWallet, “Average Car Insurance Cost in 2026” (October 2026 analysis): https://www.nerdwallet.com/insurance/auto/average-car-insurance-cost
- ValuePenguin, “Best Cheap Car Insurance in Miami,” updated Sep. 25, 2026: https://www.valuepenguin.com/best-cheap-car-insurance-miami-florida
- ValuePenguin, “Cheapest Car Insurance in Florida,” updated Oct. 13, 2026: https://www.valuepenguin.com/cheap-car-insurance-florida-study
- Florida Department of Highway Safety and Motor Vehicles, “Florida Insurance Requirements”: https://www.flhsmv.gov/insurance/
- FLHSMV, “2024 Annual Traffic Crash Facts Report”: https://www.flhsmv.gov/pdf/crashreports/2024-Crash-Report.pdf
- Florida Office of Insurance Regulation, “Commissioner Mike Yaworsky Announces More Significant Auto Rate Decreases for Florida’s Top 5 Auto Insurance Groups,” Mar. 5, 2026: floir.gov
- Florida Office of Insurance Regulation, “Hurricane Isaias” claims data (as of Oct. 15, 2026): https://floir.gov/home/hurricane-isaias
- Florida Statutes, Section 768.81, Comparative fault: http://www.leg.state.fl.us/statutes/index.cfm?App_mode=Display_Statute&URL=0700-0799/0768/Sections/0768.81.html
- Miami-Dade Sheriff’s Office, 2025 Annual Report (crime statistics): https://www.miamilakes-fl.gov/wp-content/uploads/2022/11/MDSO-2025-Annual-Report.pdf
- National Insurance Crime Bureau, “U.S. Vehicle Thefts Experience Historic Decline,” Mar. 18, 2026: https://www.nicb.org/news/news-releases/us-vehicle-thefts-experience-historic-decline
- Insurance Information Institute (Triple-I), “Facts + Statistics: Uninsured motorists” (Insurance Research Council data): https://www.iii.org/fact-statistic/facts-statistics-uninsured-motorists
- NAIC, Consumer Insurance Search: https://content.naic.org/cis_consumer_information.htm
This article is general information, not insurance advice. Prime Capital Report is not an insurer, agent or broker, and the author, Roberto Gomes, is not a licensed insurance agent. Confirm coverage and prices with a licensed provider in Florida.
Related guides
More guides from Prime Capital Report

Written by
Roberto Gomes, Founder and Editor
Roberto researches insurance and personal finance in the United States and Canada from insurers' policy documents, regulator data and public rate filings. He is not a licensed agent or adviser. How we research.