For most Florida drivers, Geico is the cheapest large car insurance company. For example, it averages about $213 a month for full coverage and $37 a month for minimum coverage, according to ValuePenguin’s October 2026 analysis. State Farm and Travelers are close behind. In addition, UAIC is often the cheapest option for drivers with poor credit. Florida is still one of the most expensive states for car insurance. However, rates are finally falling, so 2026 is a good year to compare quotes.
Key takeaways
- Cheapest overall: Geico, at an average of $213/month for full coverage and $37/month for minimum coverage (ValuePenguin, Oct 2026).
- Cheapest in NerdWallet’s analysis: Geico again, at a median of $175/month ($2,104/year) for full coverage (NerdWallet, Oct 2026). Minimum coverage costs $30/month.
- Typical cost: Florida drivers pay an average of about $311/month for full coverage and $102/month for minimum coverage (ValuePenguin). By comparison, NerdWallet’s full coverage estimate is $275/month.
- Legal minimum: $10,000 in personal injury protection (PIP) and $10,000 in property damage liability (PDL). However, Florida doesn’t require bodily injury liability for most drivers (FLHSMV).
- Rates are dropping: Florida’s five largest auto insurance groups indicated an average −8% rate change for 2026 (Florida Office of Insurance Regulation). That follows +31.7% in 2023.
Cheapest car insurance companies in Florida
The table below lists ValuePenguin’s average Florida rates for its sample driver. He’s a 30-year-old man with good credit and a clean record who drives a 2018 Honda Civic EX. In this study, “full coverage” means 50/100/50 liability, 50/100 uninsured motorist coverage, $10,000 PIP, and collision and comprehensive coverage with a $500 deductible. By contrast, “minimum” means a policy that meets the state minimum. In addition, we calculated annual figures by multiplying ValuePenguin’s monthly averages by 12.

| Company | Full coverage (monthly) | Full coverage (annual, est.) | Minimum coverage (monthly) | Minimum coverage (annual, est.) |
|---|---|---|---|---|
| Geico | $213 | $2,556 | $37 | $444 |
| State Farm | $215 | $2,580 | $67 | $804 |
| Travelers | $239 | $2,868 | $71 | $852 |
| UAIC | $255 | $3,060 | $127 | $1,524 |
| Allstate | $463 | $5,556 | Not in top 5 | — |
| Progressive | Not in top 5 | — | $138 | $1,656 |
| Florida average | $311 | $3,732 | $102 | $1,224 |
Source: ValuePenguin, Cheapest Car Insurance in Florida (updated Oct. 13, 2026; Quadrant Information Services data). UAIC stands for United Automobile Insurance Company, a Florida-based insurer. These are averages, so your quote will differ.
Shopping around matters. For example, among ValuePenguin’s five cheapest full coverage companies, Allstate ($463) costs $250 a month more than Geico ($213). Meanwhile, Geico and State Farm are only $2 apart, so quote both.
A second opinion: NerdWallet’s Florida rankings
Different studies use different sample drivers and coverage levels, so the rankings change. For example, NerdWallet’s October 2026 analysis uses a 35-year-old driver with a 2023 Toyota Camry LE. The policy has 100/300/50 liability, 100/300 uninsured motorist coverage and $1,000 deductibles. It found these as the cheapest options:
| Company | Full coverage (median monthly) | Minimum coverage (median monthly) |
|---|---|---|
| Geico | $175 | $30 |
| UAIC | $191 | $105 |
| Travelers | $197 | $51 |
| Mercury | $326 | $37 |
| Allstate | $377 | Not in top 5 |
Source: NerdWallet, The Cheapest Car Insurance in Florida (updated Oct. 2, 2026; rates refreshed Oct 2026; Quadrant Information Services data). Direct Auto ($91/month) was fourth for minimum coverage. However, NerdWallet’s analysis does not include Liberty Mutual.
Both studies put Geico first, with Travelers and UAIC consistently competitive. So quote Geico, State Farm and Travelers. Then add UAIC or Mercury if you have poor credit or want minimum coverage. Also add USAA if you’re in a military family (NerdWallet doesn’t rank USAA because eligibility is limited).
Cheapest car insurance in Florida by driver profile
Teen and young drivers
ValuePenguin found Geico cheapest for 18-year-olds, at $83 a month for minimum coverage and $527 for full coverage. However, USAA, for military families, was $48 and $264. For 20-year-olds with their own policy, NerdWallet found UAIC cheapest for full coverage ($309 a month) and Geico for minimum coverage ($58). Joining a parent’s policy is usually cheaper. For example, in NerdWallet’s May 2026 analysis, Travelers charged $438 a month for a household full coverage policy with a 20-year-old. That’s $150 more than the parents alone.
Senior drivers
Geico was cheapest for older drivers in both studies. For example, ValuePenguin’s data shows $181 a month for full coverage at age 65, $198 at 75 and $240 at 85. Similarly, NerdWallet’s shows a $156 median at age 70. Drivers 55 and older can also earn a required discount by taking a state-approved safety course (see discounts below).
After a speeding ticket
Geico was cheapest after a ticket in both studies. In fact, in each it charged the same as for a clean record. That’s $213 a month in ValuePenguin’s data (39% below the $351 state average for drivers with a ticket) and $175 in NerdWallet’s. Overall, ValuePenguin found one speeding ticket raises Florida rates by about 13%, or around $40 a month.
After an at-fault accident
State Farm was cheapest after an accident in ValuePenguin’s data, at $251 a month for full coverage, ahead of Geico at $286. By contrast, Geico ($243) and UAIC ($248) were almost tied in NerdWallet’s data. On average, one at-fault accident raises Florida rates by about 46%, or roughly $145 a month (ValuePenguin). Your insurer usually won’t raise your rate until renewal, so shop when the renewal offer arrives.
After a DUI
ValuePenguin found Travelers cheapest after a DUI, at $382 a month for full coverage (Geico was next at $423). By contrast, NerdWallet had Geico first at $301. A DUI raises Florida rates by about 68% on average (ValuePenguin). That’s partly because convicted drivers must file an FR-44 and carry 100/300/50 liability limits. In addition, causing an injury crash can also trigger an SR-22 requiring $10,000/$20,000 in bodily injury liability.
Bad credit
Florida law lets insurers use credit-based insurance scores. As a result, ValuePenguin found that drivers with poor credit pay about twice as much as those with good credit. UAIC was cheapest for them in both studies. For example, it charged $255 a month for full coverage in ValuePenguin’s data (Geico next at $394) and $192 in NerdWallet’s (Geico next at $334).
Cheapest car insurance in major Florida cities
Where you park your car is one of the biggest factors in your rate. In particular, South Florida is much more expensive than the rest of the state. The table compares ValuePenguin’s average full coverage rate with the cheapest company it found in each city. For another view, it also shows NerdWallet’s cheapest clean-record full coverage rate.
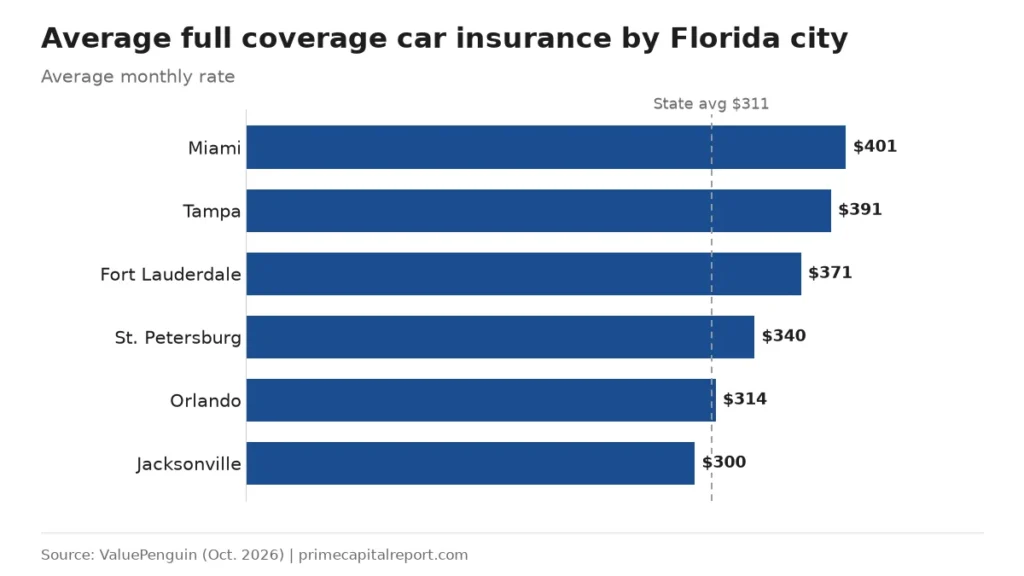
| City | Avg. full coverage (ValuePenguin, monthly) | Cheapest (ValuePenguin) | Cheapest (NerdWallet, median annual) |
|---|---|---|---|
| Miami | $401 | Geico, $224/mo | Geico, $2,267/yr |
| Tampa | $391 | Geico, $256/mo | Geico, $2,681/yr |
| Fort Lauderdale | $371 | State Farm, $267/mo | Geico, $2,869/yr |
| St. Petersburg | $340 | State Farm, $238/mo | UAIC, $2,466/yr |
| Orlando | $314 | Geico, $191/mo | Geico, $1,966/yr |
| Jacksonville | $300 | Geico, $188/mo | Geico, $1,878/yr |
Sources: ValuePenguin (Oct 2026); NerdWallet (Oct 2026). The two studies use different driver profiles, so compare rows within one column, not across columns.
Miami and Tampa are the most expensive of the six in ValuePenguin’s data. By contrast, Jacksonville and Orlando are the cheapest in both studies. Statewide, ValuePenguin found the highest average in Westview, outside Miami ($453 a month). Meanwhile, the lowest was in Santa Rosa Beach in the Panhandle ($224). Geico wins in most big cities, but State Farm has the lowest rates in 59% of Florida cities and towns. So keep it on your list outside the major metros.
Florida car insurance requirements
According to the Florida Department of Highway Safety and Motor Vehicles (FLHSMV), you must show proof of two coverages first. Only then can you register a vehicle with at least four wheels in Florida:
- $10,000 in personal injury protection (PIP). In short, PIP pays 80% of necessary and reasonable medical expenses up to $10,000, no matter who caused the crash.
- $10,000 in property damage liability (PDL). Similarly, PDL pays for damage you or someone driving your car causes to other people’s property.
Florida is a no-fault state, so after a crash you turn to your own PIP first for injuries. Under section 627.736, Florida Statutes, PIP also pays 60% of lost income and a $5,000 death benefit. But you must get initial care within 14 days of the crash. In addition, the law caps medical benefits at $2,500 unless a qualified provider finds an emergency medical condition.
Why minimum coverage isn’t enough
Unlike most states, Florida doesn’t require bodily injury liability (BIL) for most drivers. That’s risky. If you seriously injure someone, they can sue you, and minimum coverage won’t pay for their injuries or your defense. ValuePenguin notes that BIL and uninsured motorist coverage usually come standard, but you can reject them in writing. However, we don’t recommend rejecting them. In fact, an estimated 20.6% of Florida drivers had no insurance in 2023, the seventh-highest rate in the country (Insurance Research Council data via Triple-I).
The state minimum also won’t fix your own car. Only comprehensive coverage pays for hurricane, flood and fallen-tree damage. For example, ValuePenguin counts 151,892 cars that Hurricane Ian damaged in 2022. In addition, lenders require collision and comprehensive coverage on financed or leased cars.
FLHSMV requires continuous coverage for the whole registration period, even if the car sits unused. As a result, a lapse can mean a license and registration suspension of up to three years. It can also mean a reinstatement fee of up to $500, with no hardship license. Turn in your plate before canceling your insurance.
Why Florida car insurance rates changed in 2026
Florida drivers saw huge increases after the pandemic. For example, the Florida Office of Insurance Regulation (OIR) reports that the state’s top five auto insurance groups indicated an average rate change of +31.7% in 2023. Then that dropped to +4.3% in 2024 and to cuts in 2025. In March 2026, OIR said those groups (Progressive, Geico, State Farm, Allstate and USAA, which together write 78% of the market) were indicating an average −8% change for 2026. In short, these are the main reasons:
- The 2023 tort reform law (HB 837). Signed March 24, 2023, the law shortened the deadline for negligence lawsuits from four years to two. In addition, it ended one-way attorney fees in most insurance suits and barred plaintiffs who are more than 50% at fault from recovering damages (Insurance Business). As a result, Progressive says the share of its PIP claims ending in lawsuits fell about 60% since.
- Lower claim costs. OIR reports that Florida’s personal auto liability loss ratio fell to 52.5% in 2025, the lowest in the nation. Similarly, the auto physical damage loss ratio fell from 112.0% in 2022 to 49.5% in 2025. For context, a loss ratio over 100% means insurers paid out more in claims than they collected in premiums.
- Refunds and dividends. OIR says Progressive reported nearly $1 billion in credits to Florida policyholders. In addition, State Farm announced a Florida dividend averaging $173 per vehicle.
2026 rate changes by insurer
Rates are still high, though, because of hurricanes, heavy traffic and uninsured drivers. For example, ValuePenguin’s review of rate filings (as of Oct. 6, 2026) shows the biggest 2026 cuts at State Farm (−10.2%), Auto-Owners (−8.6%), USAA (−7.0%), Allstate (−5.3%) and Geico (−4.2%). Progressive and United Auto were flat, and American Family was the only major insurer with an increase (+3.6%). However, every insurer in that table is still at least 29.5% above its rates of five years ago. Also, a filing may apply only to some drivers, so your renewal can still go up.
Car insurance discounts in Florida
Florida law requires or allows several specific discounts. So ask about each one by name:
- Mature driver course (55+), required. Under section 627.0652, insurers must reduce liability, PIP and collision premiums for a principal driver 55 or older who completes an FLHSMV-approved course. The discount lasts three years. However, each insurer sets the amount.
- Driver improvement course, optional. Section 627.06501 lets insurers give up to 10% off for an approved course, for three years. However, it doesn’t apply if you took the course to settle a ticket.
- Safety and anti-theft equipment. Under section 627.0653, insurers must discount premiums for factory-installed four-wheel anti-lock brakes and air bags. They must also include comprehensive discounts for approved anti-theft or vehicle-recovery systems. They may offer discounts for VIN window etching and collision-avoidance technology.
- Insurer discounts. Multi-car, bundling, good student and usage-based (telematics) programs vary by company. For example, ValuePenguin notes Geico discounts for quoting online, quoting before your policy expires and paying automatically.
Be wary of any “discount” that removes bodily injury or uninsured motorist coverage to make a quote look cheaper. In other words, that cuts coverage. It isn’t a discount.
How to compare car insurance quotes in Florida
- Choose your coverage first. Pick your bodily injury and uninsured motorist limits, deductibles and whether you need comprehensive coverage. Then quote the same coverage everywhere.
- Get at least three quotes. Include Geico, State Farm and Travelers. Also add USAA if you’re eligible, and UAIC or Mercury if your credit is poor or you want minimum coverage.
- Use the state’s tool. OIR’s CHOICES rate comparison tool shows sample average auto rates for insurers in any Florida county. OIR says the rates are for illustration only, so you’ll still need real quotes.
- Time your shopping. Start about a month before your renewal date, when your current company sends its renewal offer.
- Re-shop every year. With most major insurers cutting Florida rates in 2026, last year’s cheapest company may not be this year’s. Moving or adding a teen driver can also change the answer.
If no company will insure you, the Florida Automobile Joint Underwriting Association (FAJUA) is the state’s “market of last resort.” Florida created it in 1973 for licensed drivers and vehicle owners who can’t buy insurance elsewhere. Comparing a different state? See our guide to the cheapest car insurance in Texas for 2026.
Our methodology
Prime Capital Report doesn’t collect insurance quotes itself. Instead, we compared current published rate studies. We also used Florida government sources for legal requirements and market trends. All rate figures are averages or medians from the source named next to them. As a result, your own quote will differ.
- Main rate data: ValuePenguin (updated Oct. 13, 2026): 442,470 quotes from six large insurers across 1,031 Florida ZIP codes (Quadrant Information Services data). It also uses OIR rate filings current as of Oct. 6, 2026.
- Second rate source: NerdWallet (rates refreshed Oct 2026): median Quadrant rates from six insurers for a 35-year-old base driver. Seniors are modeled at 70, while young drivers are modeled at 20.
- Market and trend data: Florida Office of Insurance Regulation releases (July 2025 and March 2026), Insurance Business, and the Insurance Research Council through Triple-I.
- Legal requirements and discounts: FLHSMV and the Florida Statutes (sections 627.736, 627.0652, 627.06501 and 627.0653).
In addition, annual figures marked “est.” are monthly averages multiplied by 12. We don’t mix sources within a single ranking, because each study uses a different driver profile. We’ll update this page when the sources refresh their data.
Frequently asked questions
What is the cheapest car insurance company in Florida?
For most drivers, Geico is the cheapest large insurer in Florida. For example, ValuePenguin’s October 2026 averages are $213 a month for full coverage and $37 for minimum coverage. NerdWallet’s October 2026 analysis also ranked Geico cheapest, at a median of $175 a month for full coverage. State Farm ($215) and Travelers ($239) are close behind in ValuePenguin’s data.
How much is car insurance in Florida per month in 2026?
ValuePenguin puts the Florida average at about $311 a month for full coverage and $102 a month for minimum coverage. By comparison, NerdWallet’s full coverage estimate is $275 a month, or $3,295 a year. That’s well above its national average of $2,361 a year.
What is the minimum car insurance required in Florida?
Florida requires $10,000 in personal injury protection (PIP) and $10,000 in property damage liability (PDL). Most drivers don’t have to carry bodily injury liability. However, we strongly recommend buying it, because someone can still sue you if you seriously injure them.
Which Florida city has the cheapest car insurance?
Among the six large cities we compared, Jacksonville ($300 a month) and Orlando ($314) have the lowest average full coverage rates in ValuePenguin’s data. By contrast, Miami ($401) and Tampa ($391) are the most expensive. Statewide, ValuePenguin found the lowest average in Santa Rosa Beach ($224 a month).
Are Florida car insurance rates going down in 2026?
For many drivers, yes. The Florida Office of Insurance Regulation says the state’s five largest auto insurance groups indicated an average −8% rate change for 2026. Similarly, ValuePenguin’s filing data shows cuts at State Farm (−10.2%), USAA (−7.0%), Allstate (−5.3%) and Geico (−4.2%). However, individual renewals can still go up.
How did the 2023 tort reform affect Florida car insurance?
HB 837, signed in March 2023, shortened the deadline for negligence lawsuits from four years to two. It also ended one-way attorney fees in most insurance suits and barred plaintiffs more than 50% at fault from recovering damages. OIR credits the law with lower loss ratios and the rate cuts insurers filed in 2025 and 2026.
Who has the cheapest car insurance in Florida with bad credit?
UAIC was cheapest for drivers with poor credit in both studies, at $255 a month for full coverage in ValuePenguin’s data and $192 a month in NerdWallet’s. Florida law allows insurers to use credit-based insurance scores. As a result, ValuePenguin found that poor credit roughly doubles Florida rates.
What if no insurance company will cover me in Florida?
You can apply through the Florida Automobile Joint Underwriting Association (FAJUA). It’s the state’s market of last resort for licensed drivers and vehicle owners who can’t buy coverage from other companies. FAJUA describes itself as the high-risk market, so keep comparing regular insurers as your record improves.
Sources
- ValuePenguin, “Cheapest Car Insurance in Florida (Best Rates in 2026),” updated Oct. 13, 2026: https://www.valuepenguin.com/cheap-car-insurance-florida-study
- NerdWallet, “The Cheapest Car Insurance in Florida for October 2026,” updated Oct. 2, 2026: https://www.nerdwallet.com/insurance/auto/cheap-car-insurance-florida
- Florida Office of Insurance Regulation, “Commissioner Mike Yaworsky Announces More Significant Auto Rate Decreases for Florida’s Top 5 Auto Insurance Groups,” Mar. 5, 2026: floir.gov
- Florida Office of Insurance Regulation, “Florida Office of Insurance Regulation Announces Lower Auto Insurance Rates Thanks to Florida’s Insurance Reforms,” Jul. 29, 2025: floir.gov
- Florida Office of Insurance Regulation, CHOICES Rate Comparison Tool: https://floir.gov/consumers/choices-rate-comparison-search
- Florida Department of Highway Safety and Motor Vehicles, “Florida Insurance Requirements”: https://www.flhsmv.gov/insurance/
- FLHSMV, “Mature Driver Discount Insurance Courses”: https://www.flhsmv.gov/driver-licenses-id-cards/mature-driver/mature-driver-discount-insurance-courses/
- Florida Statutes, sections 627.736, 627.0652, 627.06501 and 627.0653 (The Florida Senate): 627.736, 627.0652, 627.06501, 627.0653
- Insurance Information Institute (Triple-I), “Facts + Statistics: Uninsured motorists” (Insurance Research Council data): https://www.iii.org/fact-statistic/facts-statistics-uninsured-motorists
- Insurance Business, “Insurers cut Florida rates on strong earnings,” Mar. 9, 2026: https://www.insurancebusinessmag.com/us/news/auto-motor/insurers-cut-florida-rates-on-strong-earnings-567842.aspx
- Florida Automobile Joint Underwriting Association: https://fajua.org/
Related guides
More guides from Prime Capital Report

Written by
Roberto Gomes, Founder and Editor
Roberto researches insurance and personal finance in the United States and Canada from insurers' policy documents, regulator data and public rate filings. He is not a licensed agent or adviser. How we research.